
Ethiopia is establishing its first specialised mortgage refinancing company, capitalised at 100 billion birr ($620 million), with the International Finance Corporation (IFC) — the private-sector arm of the World Bank Group — committing up to $200 million to the initiative.
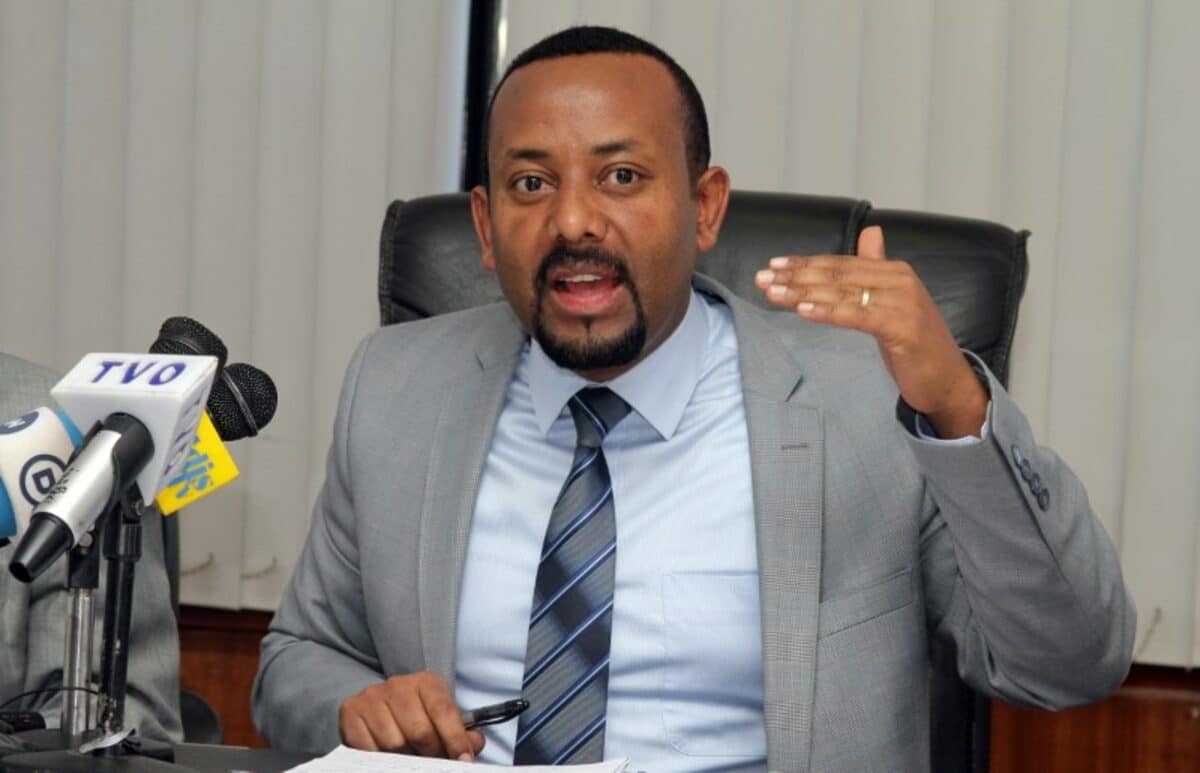
The National Bank of Ethiopia (NBE) and IFC have signed a cooperation framework for the institution, Prime Minister Abiy Ahmed announced. The company is designed to address a structural constraint common to emerging African financial systems: the mismatch between the short-term deposits that banks rely on for funding and the long-term capital that mortgage lending requires.
By acting as a wholesale intermediary, the refinancing company would allow banks to pledge eligible mortgage assets in exchange for longer-term liquidity — freeing up balance-sheet capacity to issue new housing loans rather than holding existing ones to maturity.
A market built around one lender
Ethiopia’s mortgage market is both small and heavily concentrated. The Centre for Affordable Housing Finance in Africa estimates outstanding mortgage loans at approximately 24.1 billion birr, with the Commercial Bank of Ethiopia (CBE) holding roughly 69% of that portfolio.
Private banks have struggled to build meaningful mortgage businesses, partly because access to long-term funding has been limited.
The proposed capital base is therefore substantial relative to the existing mortgage stock — a signal that the government is attempting to build an institution capable of supporting a far larger market, not merely plugging a marginal funding gap.
A functioning refinancing facility could lower the balance-sheet burden of holding long-duration housing loans and make the sector more attractive to private lenders, gradually reducing CBE’s dominance.
Liquidity alone will not solve affordability
The initiative sits within a broader policy context.
Abiy linked the refinancing company to a government target of delivering 1.5 million affordable homes and expanding private-sector participation in financial services. The institution would not itself build homes, but could remove a central financing bottleneck by creating a wholesale source of longer-term capital for banks.
However, the source of funding is only part of the challenge. Ethiopia’s banks have recently entered a new interest-rate environment following the NBE’s decision to allow lenders to set their own lending and deposit rates. Commercial lending rates have remained high, meaning the cost of a mortgage — not just its availability — will determine whether expanded liquidity translates into expanded home ownership.
The refinancing company will therefore need to do more than mobilise capital. To shift the economics of housing finance for ordinary households, it will need to help create mortgage products with lower funding costs and longer maturities, supported by stronger credit infrastructure and an adequate supply of affordable housing stock.
The architecture being proposed — a specialised intermediary connecting banks with longer-term capital markets — mirrors models used in more developed housing-finance systems and has been attempted with varying degrees of success elsewhere on the continent.
IFC’s participation adds international development-finance credibility to the effort, though the structure and terms of its $200 million contribution have not been disclosed.
If it functions as intended, the institution could shift Ethiopian housing finance from a model in which each bank funds mortgages largely from its own deposit base to one in which mortgage lending operates as a scalable, market-based financial segment.
The broader lesson for African markets with similar structural constraints — concentrated banking sectors, short-term deposit funding, and thin mortgage markets — will depend on how Ethiopia navigates the gap between mobilising capital and making home ownership genuinely accessible.