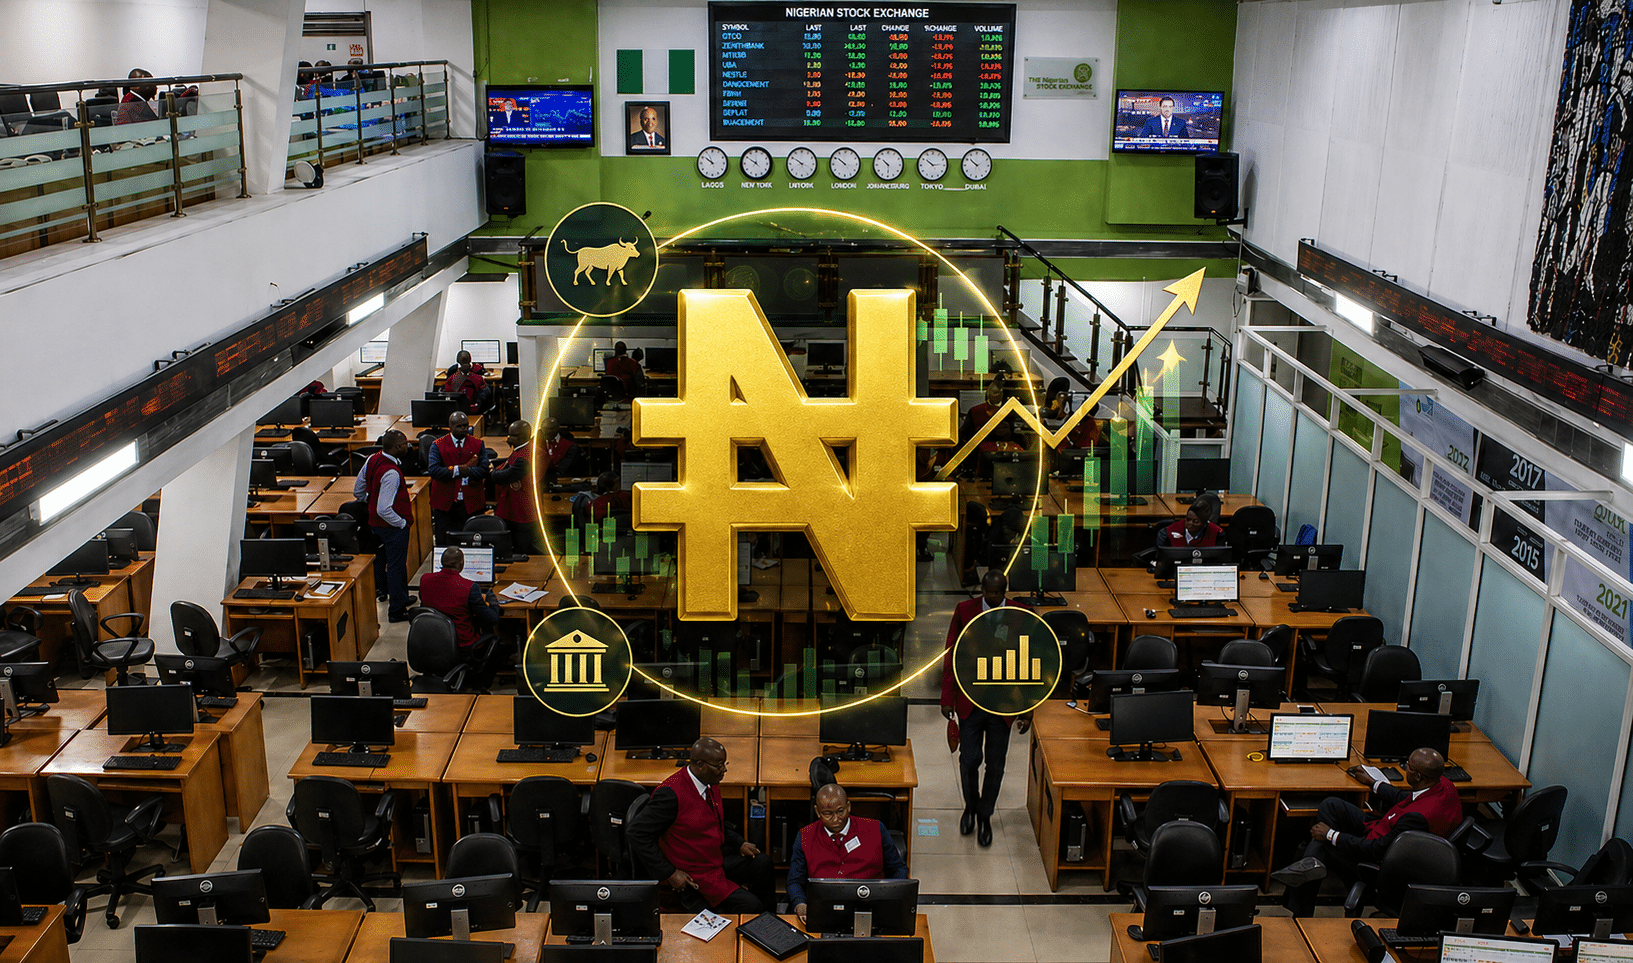


Nigeria’s stock market has spent much of 2026 breaking records. In May, market capitalisation crossed N160 trillion ($116.3 billion) for the first time ever. By July, the Nigerian Exchange (NGX) was named the world’s best-performing equity market in dollar terms.
The rally carried into August. After recovering from a sharp sell-off in June, the NGX climbed back to its May peak on August 10.
Then it weakened again.
Over the next 10 trading sessions, nearly N6 trillion ($4.44 billion) was wiped off the market as investors took profits. The selling continued through the rest of the month, with the NGX falling in 13 of August’s 20 trading sessions.
This was not the first time investors had taken profits after a spectacular run.At some point, more than N13 trillion ($9.45 billion) was wiped off the market after months of extraordinary gains. But that correction proved short-lived. Buyers only returned as cheaper shares offered more attractive valuations, and turnover jumped.
However, August has been harder to shake off. The market is still well ahead for the year, but the buyers who stepped in after June’s sell-off have been slower to return.
This matters because the market is not short of reasons to be optimistic.
A rally that changed the market
The latest sell-off comes after one of the market’s strongest runs in years. In the first seven months of the year alone, market capitalisation rose by N58.9 trillion ($43.6 billion), while the All-Share Index gained more than 50%.
At its August peak of N160.3 trillion ($118.7 billion), the market was worth five times its 2023 value.
Much of that enthusiasm reflected a broader repricing of Nigerian assets. The naira floating reforms that initially caused severe disruption to the naira also began to change the investment case as foreign-exchange liquidity improved and the currency became more stable. Inflation has also moderated sharply, while companies—particularly banks—reported earnings that gave investors something tangible to support higher valuations.
Domestic investors were at the centre of the surge. In July, they accounted for 94.4% of NGX transactions, leaving foreign investors with just 5.6%. The rally was therefore not simply a return of international money to Nigeria. Local institutions and individuals were putting substantially more of their savings into equities.
The gains were extraordinary at the stock level, too. Some companies delivered triple-digit returns, with the best performers rising several hundred per cent. At the same time, the benchmark had gained about 67% against the dollar year to date, putting Nigerian equities at the top of the global rankings.
That kind of performance can create its own momentum. Rising prices attract attention; attention brings more buyers; and each new gain makes equities harder to ignore.
It also leaves investors with something to protect.
NGX executives told President Bola Tinubu in August that market capitalisation could reach N230 trillion ($170.2 billion) before the end of the year.
That target shows how much expectations have changed. Three years ago, a N160 trillion ($116.3 billion) market would have seemed distant. Now the question is whether investors have enough reasons to keep pushing it higher.
More than investors locking in profits
August’s decline was hardly surprising after the market’s record-breaking run. Investors had made large gains, and some were bound to take money off the table.
The scale of the rally also raises a harder question: whether prices had simply outrun what earnings and growth could justify, making some correction inevitable regardless of what investors did with the proceeds. But analysts say the sell-off may be about more than that.
Capital is facing more competition, and some investors may be choosing where to deploy their money rather than simply leaving equities.
That distinction matters.
Sylvester Anaba, head of research at United Capital, says investors do not necessarily sell because they have turned negative on Nigerian equities. “Sometimes they sell because they need cash for an opportunity they believe could offer a better return,” Anaba told BusinessFront.
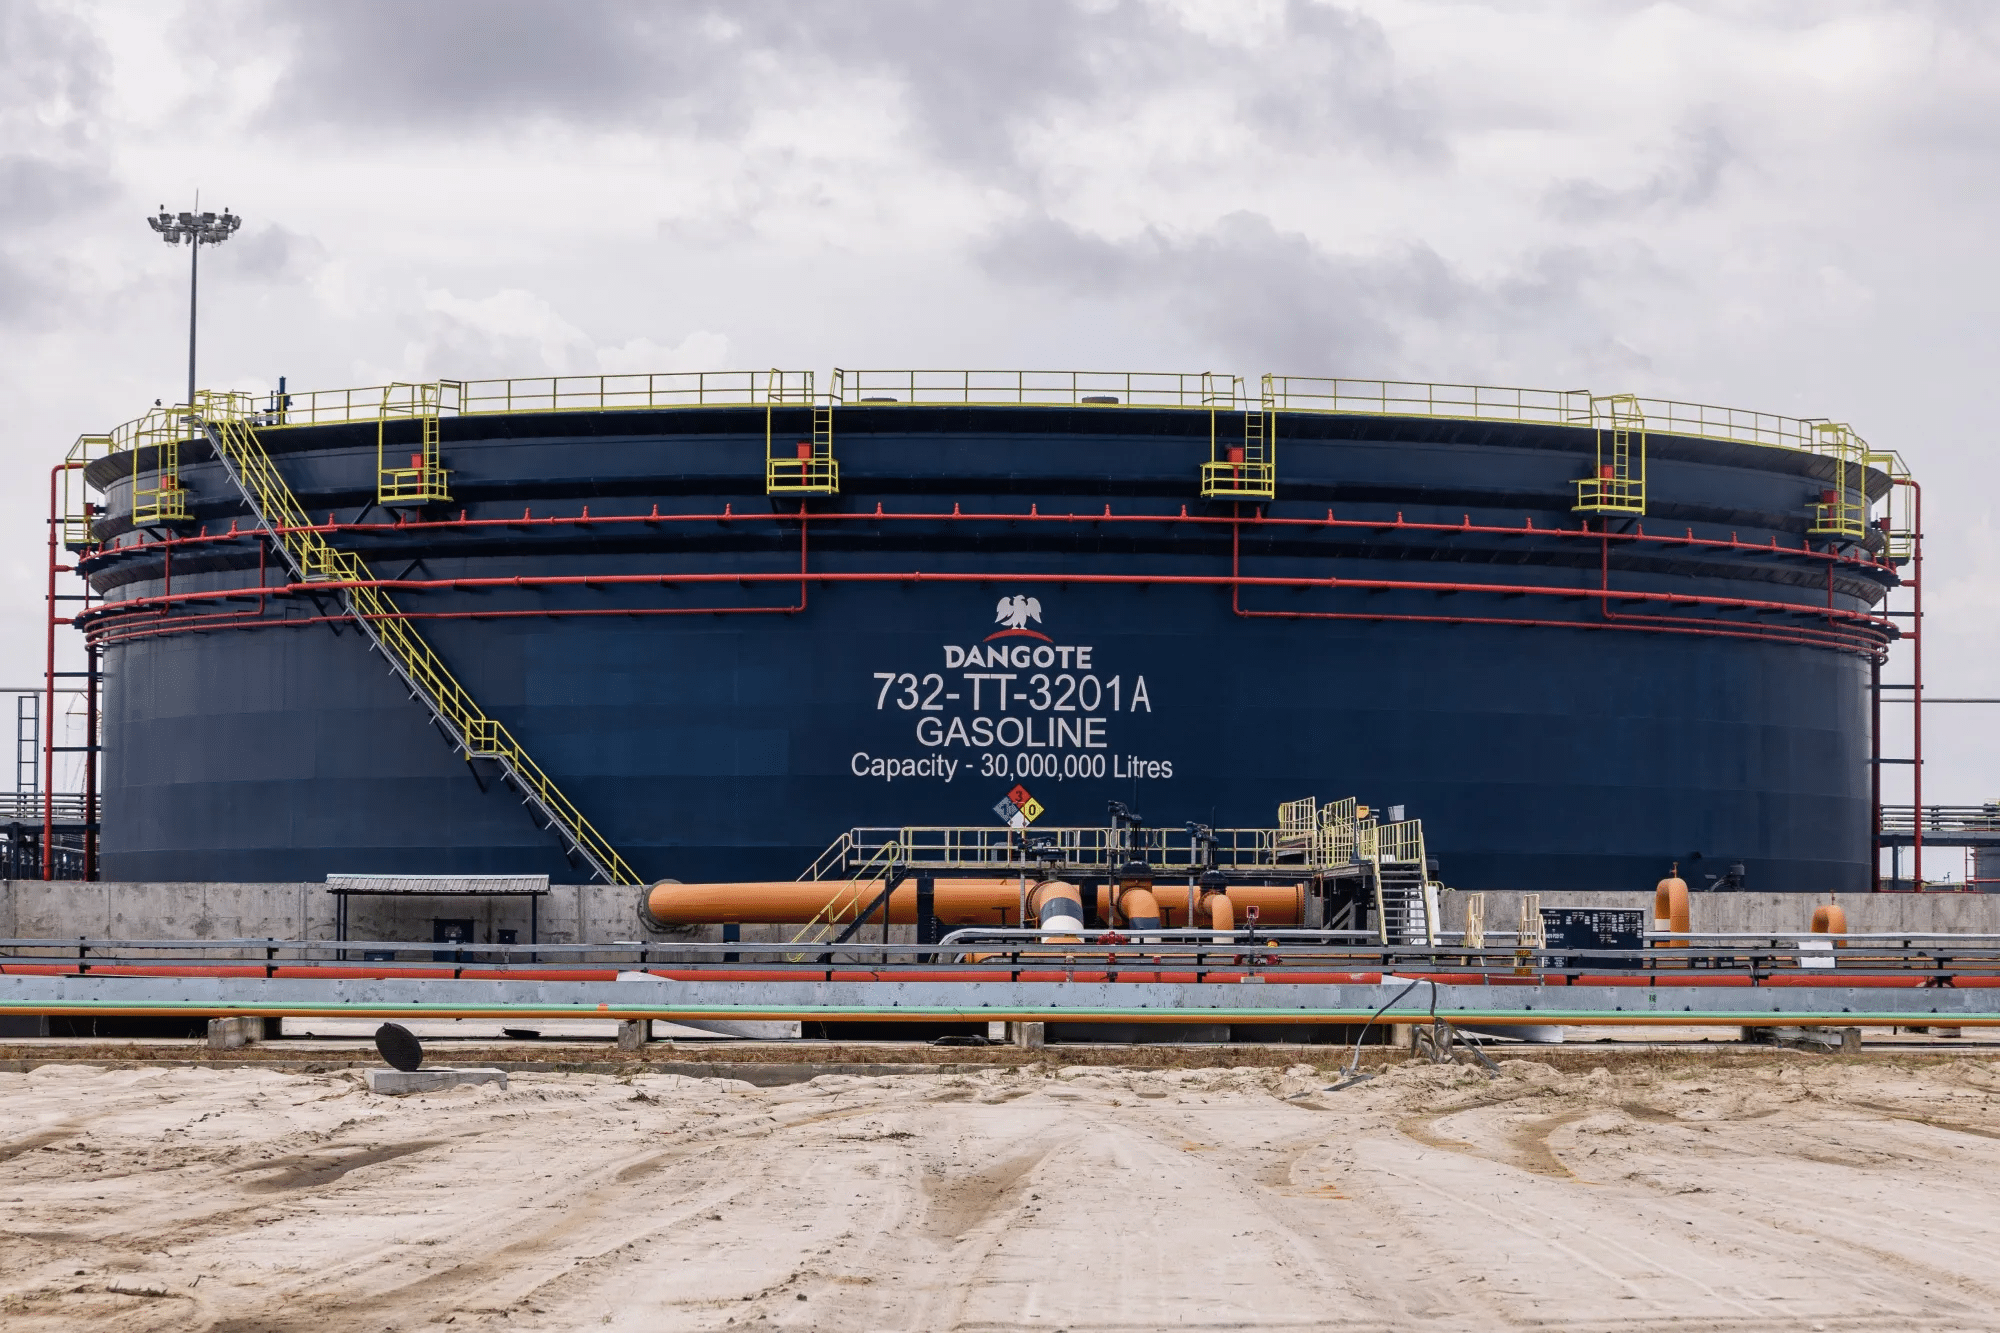
One such opportunity is already taking shape. Investors are positioning for the possible October listing of Dangote Refinery, which would be Africa’s largest-ever initial public offering if it hits its $5 billion target. The refinery has already tested investor interest: Dangote said in July that a $2.5 billion private placement was 3.7 times oversubscribed.
A transaction of that size could compete for some of the same domestic capital that has powered this year’s equity boom. An investor who has made a large gain on a bank or industrial stock does not have to leave the market entirely. Selling part of the position can free up cash for a new opportunity.
The selling has been concentrated in some of the market’s largest and most liquid stocks. Consumer food producer BUA Foods lost about N1.52 trillion ($1.13 billion) in market value between August 10 and August 21, while MTN Nigeria shed about N1.39 trillion ($1.03 billion). Together, they accounted for almost half of the roughly N5.9 trillion ($4.37 billion) wiped off the market during that period.

That pattern is consistent with investors raising cash: large, liquid stocks are easier to sell in size than thinly traded counters. It does not, however, show where that money went.
Anaba sees Dangote’s offering as part of a broader competition for capital.
“There is also competition from other capital-market opportunities,” he said. Investors are not looking only at secondary-market equities. With several capital-raising opportunities available, he said, money committed to one transaction leaves less available for another.
That competition extends beyond new share offerings. Investors now have another reason to keep money in short-term securities.
Fixed income gives investors somewhere to wait
The Central Bank of Nigeria (CBN) has given investors another reason not to rush back into shares. In a circular issued on August 12, it lifted a seven-year restriction on Open Market Operations (OMO), opening the market to individuals, companies and non-bank financial institutions through banks.
Demand was immediate. Investors bid N4.93 trillion ($3.65 billion) for N600 billion ($444 million) of OMO bills at the next auction, pushing yields to around 20%.
That is a useful alternative after a stock market rally of more than 50%. Investors need not decide that shares are overvalued. They can simply wait for a better price while earning a respectable return elsewhere.
Treasury bills tell the same story. Investors bid N3.63 trillion ($2.69 billion) for N500 billion ($370 million) of one-year bills at the August 26 auction, with the stop rate settling at 17.15%.
With inflation at 15.43% in July, short-term government securities still offered a sizeable cushion above rising prices.
None of this guarantees that money will leave equities. It does, however, make the competition for it tougher. A share now has to offer enough upside to compensate investors for passing up high fixed-income yields.
Cordros Research expects that tension to persist. “The CBN’s revised OMO framework could temper market participation, as attractive short-term fixed-income yields may continue to compete with equities for investor flows,” the research firm said in a recent note.
The question facing the market is therefore not simply whether investors still like Nigerian shares. It is whether they like them enough to keep buying when other assets are paying so much to wait.
What could bring buyers back?
Nothing pulls money back into equities faster than proof that the earnings justify the price. That’s why Anaba calls Q3 results “probably the most important” source of fresh liquidity. Strong revenue growth, resilient margins and improving profitability could persuade investors who sold at higher prices to return, particularly where the correction has brought valuations down.
First HoldCo offers an early indication of what that could look like. Its first-half profit before tax jumped 83.5% to N653.5 billion ($475 million). If similar strength shows up across other large-cap companies, falling share prices could become more attractive relative to earnings. This would provide evidence against the idea that the rally had simply outrun fundamentals, rather than for it. Nigeria’s gross domestic product growth accelerating to 4.43% in the second quarter, from 3.89% in the first, points the same way.
There is also a sizeable pool of domestic money that could move with valuations. “Nigeria’s pension industry remains a significant pool of long-term domestic capital,” Anaba noted. In July, pension assets reached ₦31.48 trillion ($23.3 billion), up 51% in two years. Much of that money is invested in fixed income, leaving room for institutions to shift some of it if equities become more compelling.
Foreign investors could add another source of demand. They accounted for roughly one in 18 NGX transactions in July. Anaba argues that a more stable currency, better FX liquidity and greater confidence in the economy could encourage fresh foreign portfolio flows.
Those conditions are already improving. The naira has appreciated 4.52% against the dollar this year, while reserves have climbed a near-two-decade high. Foreign investors aren’t obligated to follow improving fundamentals, but the case for staying away is weaker than it was during the period of acute currency and economic stress.
Nigeria is also about to become easier for some of those investors to access. FTSE Russell will restore the country to its Frontier Market index on September 21, giving funds that track the benchmark a reason to reassess the country’s equities. The reclassification follows the NGX’s move to T+1 settlement, which FTSE said had resolved earlier concerns around settlement and funding.
The next rally leg could belong to earnings, not sentiment. First HoldCo’s 83.5% profit jump is one data point; Q3 season will supply the rest. If large-cap results hold up, the N230 trillion ($170.2 billion) target NGX executives raised with Tinubu becomes plausible rather than aspirational. If they don’t, the money that spent this year chasing equities might keep finding a home in OMO and Treasury bills instead.
NB: The naira figures were converted to US dollars using ₦1,376/$1 for H1-dated figures as applicable and N1,351/$1 for post-H1 figures (July onward, reflecting the naira’s appreciation during the period).