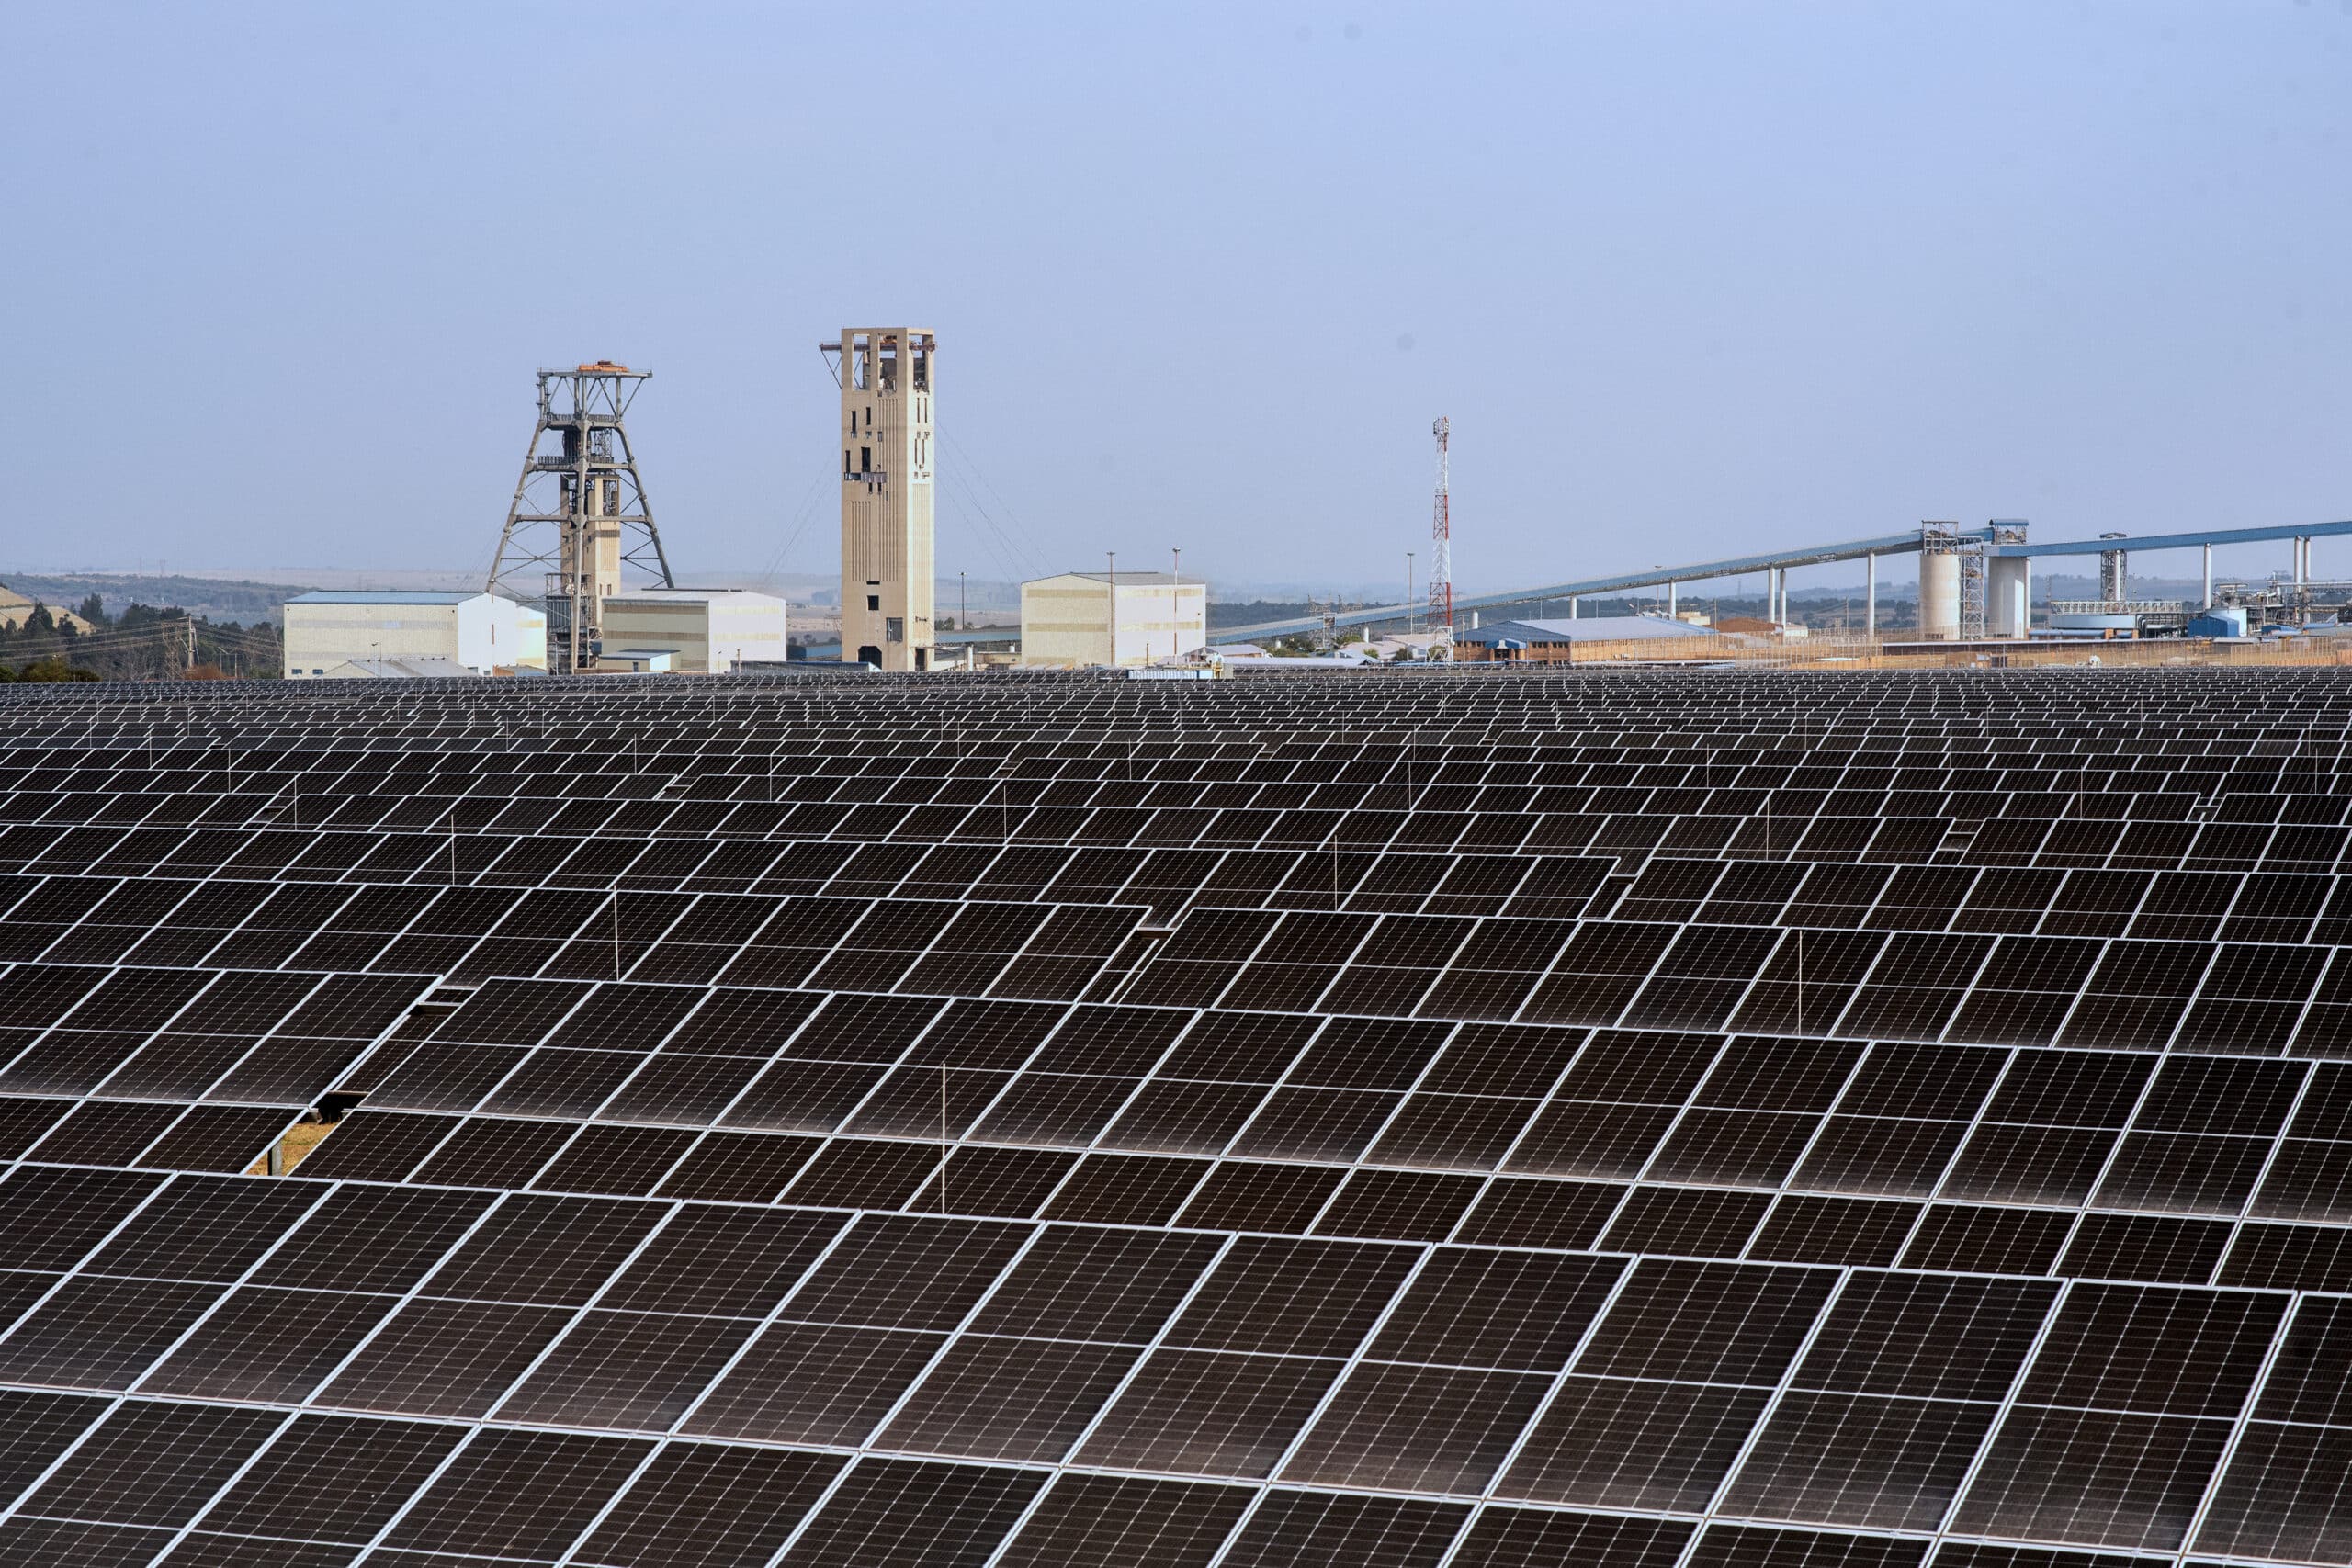


Nigeria has spent years investing in solar projects. The harder question has always been what happens after they are built.
Solar infrastructure does not stop needing money once it is commissioned. Panels degrade. Batteries need replacing. Mini-grids need operators. Customers need to keep paying. Projects also need reliable records if they are ever going to attract another round of financing.
Here is the problem the government is now trying to address with the Renewable Asset Management Company, or RAMCO. The Rural Electrification Agency (REA) says the company will launch on August 26 and is being developed with the Ministry of Finance Incorporated (MOFI) and the Infrastructure Corporation of Nigeria (InfraCorp).
RAMCO is meant to manage renewable energy assets after they have been built, improve their performance and create a structure through which they can attract long-term capital.
If it works, existing renewable infrastructure could become part of the financing for Nigeria’s next wave of solar projects. If it does not, RAMCO risks becoming another public institution holding assets that still depend on government and development finance.
Understanding what RAMCO really is
RAMCO began with a problem inside Nigeria’s renewable energy market. The government and its development partners have spent years financing mini-grids, solar home systems and other decentralised energy projects. But those investments do not automatically remain productive after they are handed over.
The REA has therefore been working towards a structure that can hold and manage renewable assets over their full operating life. Aliyu first spoke publicly about the proposal in 2025, describing a company that would warehouse renewable infrastructure on its balance sheet. In December, he said the government was considering a N500 billion capital market raise backed by renewable assets worth between $200 million and $300 million.
Those numbers are proposals, not money already raised. RAMCO has not yet demonstrated that its assets can support a capital-market transaction. The first question is therefore not how much money it can raise, but whether the assets transferred to it will have the revenue and operating records needed to support that financing.
The company is also not supposed to become another solar developer. Its proposed role is closer to an asset manager. It would take responsibility for the infrastructure, monitor its performance and organise assets in a way that makes their value easier to understand.
Aliyu described the model as one that could keep mature renewable assets productive while allowing them to be refinanced or used to support new projects. He added that this would shift attention from simply deploying infrastructure to maintaining its productivity and financial performance.
Nigeria has often treated infrastructure delivery as the end of a project. RAMCO is based on the idea that it should be the beginning of another financial cycle.
RAMCO wants to turn existing solar assets into new capital
The most interesting part of RAMCO is what happens to an asset after it has been built.
Under the new model, renewable assets could be brought into RAMCO, managed as a portfolio and improved where necessary. Once those assets have a reliable operating record, they could potentially be refinanced. The money released could then support new renewable projects.
This creates a different way of thinking about public investment. Instead of government or development partners having to provide fresh money for every project, an existing asset could eventually help fund the next one.
The logic is already visible in Nigeria’s off-grid market. Private investors have shown that they will finance distributed energy projects when the commercial structure is clear. In July, the REA said Nigeria had secured $155 million in new clean energy investments, including an $80 million debt facility for off-grid solar home systems and business power solutions.
The challenge is taking that investor interest beyond individual projects. RAMCO could provide a structure for doing that. A portfolio of operating mini-grids and other renewable assets may be more useful to a long-term investor than a collection of disconnected projects held under different government programmes.
It could also create a market for assets that have already been built. A developer or public agency would not necessarily have to hold an asset indefinitely. If the project performs well, it could potentially be transferred into a larger portfolio, refinanced or sold to another investor.
Nigeria’s renewable energy challenge will no longer simply be about deploying equipment. It will be about creating financial structures that can keep capital moving through the sector.
The real test is whether investors will trust the model
No doubt, the idea sounds promising. The difficult part will be convincing investors that the assets RAMCO manages are worth financing.
Investors will want to know what each asset earns and how stable that income is. They will want to know who owns the project, who operates it and who carries the risk. They will also need clear information on maintenance costs, equipment life, tariffs and liabilities. Without that information, the value of the portfolio will be difficult to establish.
Ibrahim Aishat, a renewable energy expert, says RAMCO’s success will depend on whether it can give investors enough visibility into the performance of the assets it manages.
“The real test is whether investors will trust the model. Investors need to see clear revenue, operating history, and who owns the risk on each asset. Without that transparency, even government-backed portfolios won’t raise capital. RAMCO needs to prove all of these,” she told Businessfront.
That is the central challenge. Government backing does not automatically make a solar project bankable. Investors will still want to understand the cash flow, the contracts and the risks before putting money behind the portfolio.
RAMCO will also have to distinguish between strong and weak assets. Some projects may have reliable revenue while others may need repairs, better management or a different commercial structure. If weak projects are simply hidden inside a larger portfolio, investors could struggle to judge what they are actually buying.
The company will therefore need strong financial reporting and reliable operating data. Its credibility will depend as much on the quality of the information it provides as on the number of assets it controls.
That is why the launch itself will not tell Nigeria whether RAMCO works. The more important test will come when the company tries to convince investors to put a price on those assets.
Execution will decide RAMCO’s impact
Moreover, Nigeria is already building the asset base that RAMCO would need.
The country added 3.1GW of small-scale solar capacity across 2024 and 2025, taking cumulative installed capacity to about 6GW. That growth means the question of how these assets are maintained and financed is becoming harder to ignore.

The same shift is visible in government programmes. REA recently began rolling out more mini-grid projects under the Distributed Access through Renewable Energy Scale-up programme, while new private financing is entering off-grid solar.
David Daniel, an energy analyst, says RAMCO’s importance will ultimately depend on whether it can turn that growing pool of renewable assets into a credible financing base.
“Nigeria now has the asset base. The next test for RAMCO is simple. Can it manage these assets commercially and transparently enough to make them bankable? If yes, then we have a real mechanism for recycling capital. If it can’t, it becomes just another public vehicle,” he told Businessfront.
That captures the opportunity. An asset built with public or development finance would not necessarily have to depend on the same source of money throughout its life. It could be maintained, consolidated and refinanced, with capital raised against existing projects helping to support new ones.
But that outcome is not guaranteed. RAMCO will need enough independence to make commercial decisions. Investors will need confidence in its accounts and asset management. Developers will need a reason to work with it. Regulators will also need to provide enough certainty for long-term investment.
The timing matters because Nigeria is producing more renewable assets while the need for long-term capital remains. If RAMCO can manage those assets properly, it could give investors a clearer route into a market that has often depended on government programmes and development finance.
That would make RAMCO more than another government renewable energy initiative. It could become part of the financial infrastructure behind Nigeria’s solar market.
Nigeria does not only need more solar panels. It needs a better way to manage the ones it has already built and use them to finance what comes next.